U.S. hospitals continue to operate in a volatile healthcare landscape. While initial post-pandemic recovery offered glimpses of stability, health organizations have spent the past year contending with a range of chronic challenges–from rising patient acuity to widening coverage gaps. Federal policy shifts and market pressures have imposed additional financial burdens on hospital leaders while further complicating their efforts to maintain and improve their quality of care.
However, amid these challenges are new opportunities for growth and improvement. The 2027 Healthgrades Specialty Excellence Report explores the top issues hospitals face as they strive for economic stability and offers insight into how organizations can leverage their clinical outcomes and protect their bottom line.
Healthgrades published this report with the release of its 2027 Specialty Excellence Awards and Ratings and 2027 Specialty State Rankings. These achievements recognize hospitals that deliver consistently better-than-expected outcomes across 31 common procedures and conditions. For its 2027 analysis, Healthgrades evaluated risk-adjusted complication and mortality rates at approximately 4,500 U.S. hospitals to identify the state and national leaders in specialty care. Healthgrades’ 2027 recognitions for excellence in inpatient specialty care include state rankings, five-star ratings, and three national awards:
- Healthgrades Specialty Excellence Award™ – the top 15% of hospitals nationwide in 19 specialties
- Healthgrades America’s 100 Best Hospitals Award™ – the top 100 hospitals nationwide in 11 specialties
- Healthgrades America’s 50 Best Hospitals Award™ – the highest achievement Healthgrades offers for inpatient specialty care; recognizes the top 50 hospitals nationwide in three specialties
- Healthgrades Specialty State Rankings™ – the top three or top five hospitals in 30 eligible states across 19 specialties1
Alongside these inpatient achievements, Healthgrades announced the recipients of its 2027 Outpatient Awards, which recognize the top 15% of hospitals nationwide in growing service areas:
- Healthgrades Outpatient Joint Replacement Excellence Award™
- Healthgrades Outpatient Orthopedic Surgery Excellence Award™
- Healthgrades Outpatient Prostate Care Excellence Award™
Specialty care is not a monolith: a five-star rating in total knee replacement does not guarantee superior performance in cardiovascular interventions or neurosciences. Objective, service-line-specific metrics provide consumers with the guidance they need to choose care based on what matters most: clinical outcomes.
Consumers can find resources on how to find a specialist and more through Healthgrades’ Patient Advocacy Center. Health systems interested in learning more about their 2027 specialty care achievements can contact a Healthgrades team member.
2027 Hospital Ratings & Consumer Survey Insights
Access to outcomes-based hospital performance indicators has never been more valuable to U.S. healthcare shoppers. Patients increasingly approach elective procedures as informed consumers, relying on third-party quality awards to choose where they receive care.
A 2026 Healthgrades consumer survey reveals the extent to which hospital quality is shaping consumer healthcare decision making:
- When deciding between two doctors for an upcoming procedure, over two-thirds of patients are more likely to choose a doctor who can treat them at a hospital with high quality ratings in their service area.2
- 71% say they’re more likely to switch to a doctor affiliated with a higher-rated hospital.2
- Nearly 70% say they would only choose a hospital with high ratings for their procedure or condition.2
Patients seeking care at a hospital with specialty care distinctions from Healthgrades should feel confident that they are maximizing their chance of a positive outcome. According to Healthgrades’ specialty care analysis:
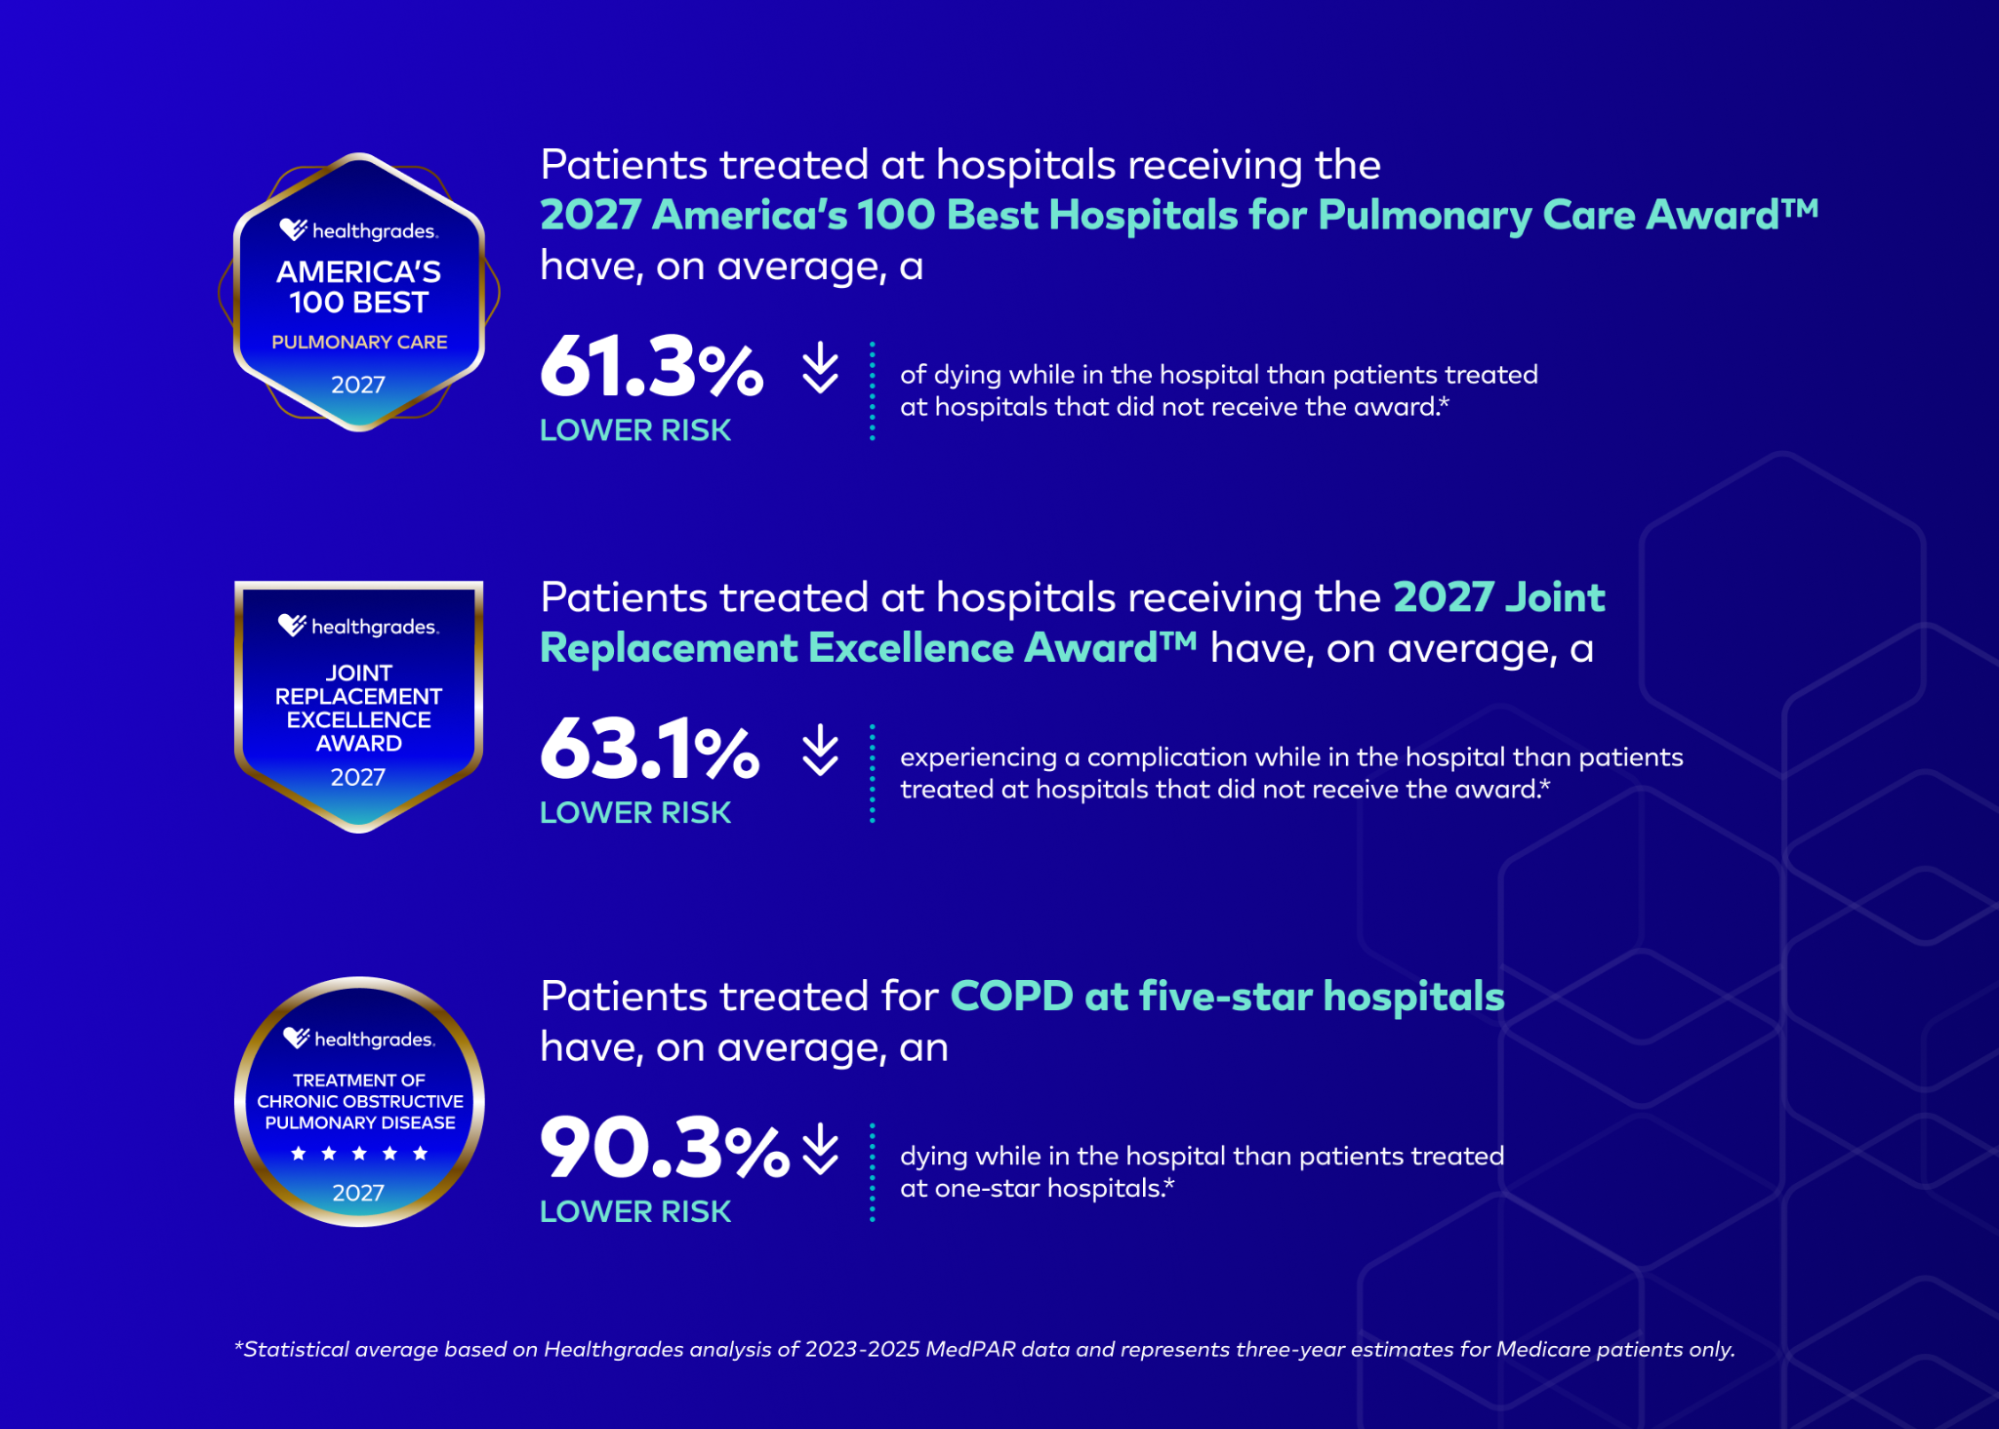
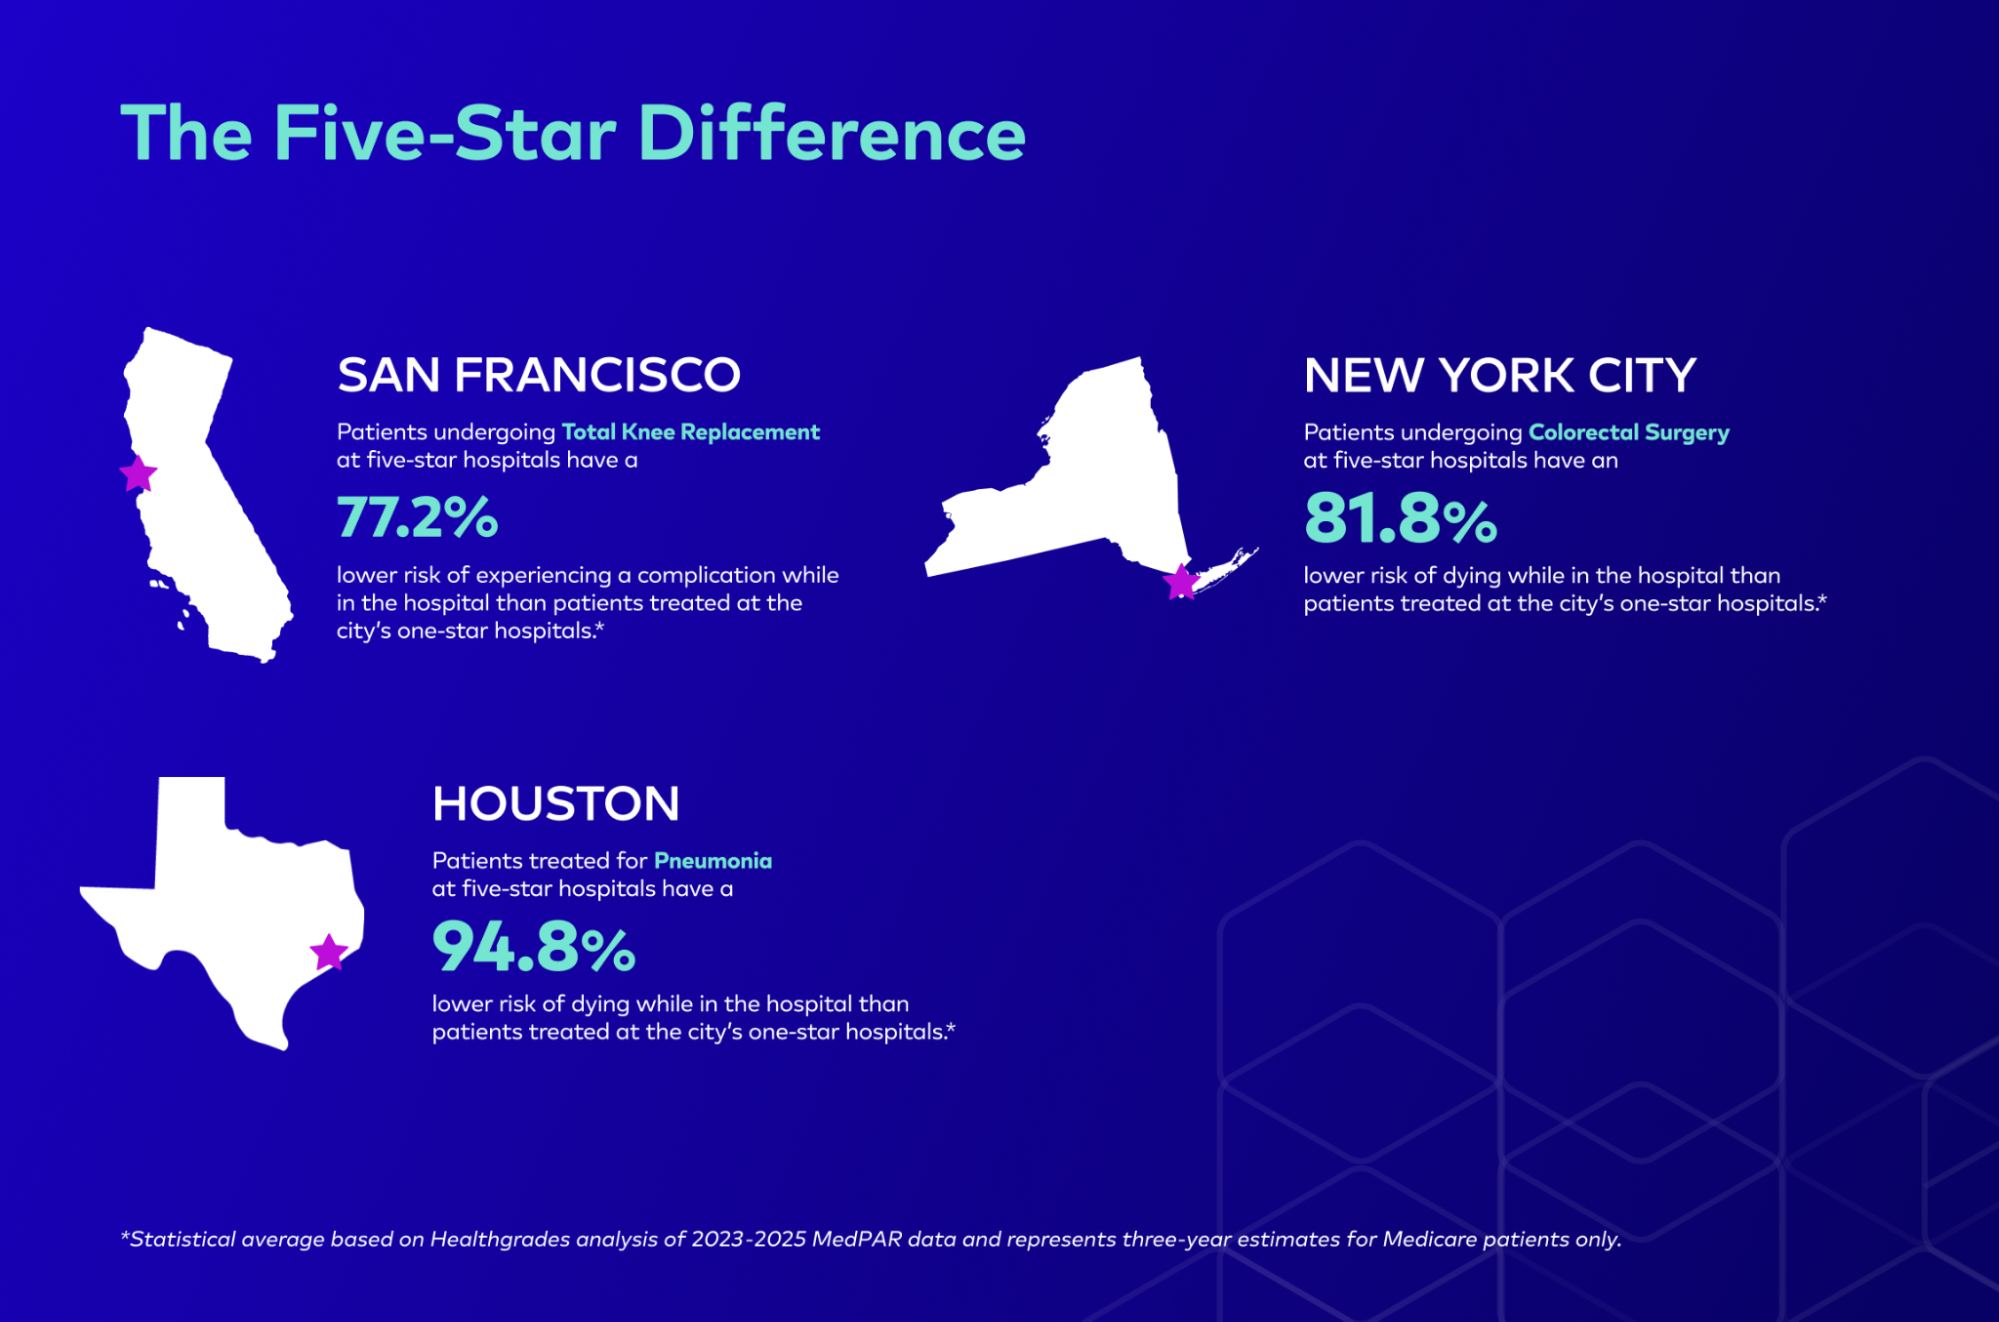
In addition to showcasing incredible achievements in specialty care, Healthgrades’ analysis highlights a widening performance gap between five-star and one-star facilities not only nationally but also within the same regional markets. Patients who seek care at low-performing facilities face significantly higher risks of complications and mortality. These findings further underscore the importance of providing consumers with data-driven resources to identify care solutions that meet their unique health needs.
Likewise, Healthgrades’ award and rating analysis offers hospitals valuable insights into their clinical strengths and weaknesses, as well as opportunities to improve their care. Informed healthcare decision making and targeted clinical improvement are both vital to elevating patient outcomes, particularly as the achievement gap between the nation’s five- and one-star hospitals continues to grow.
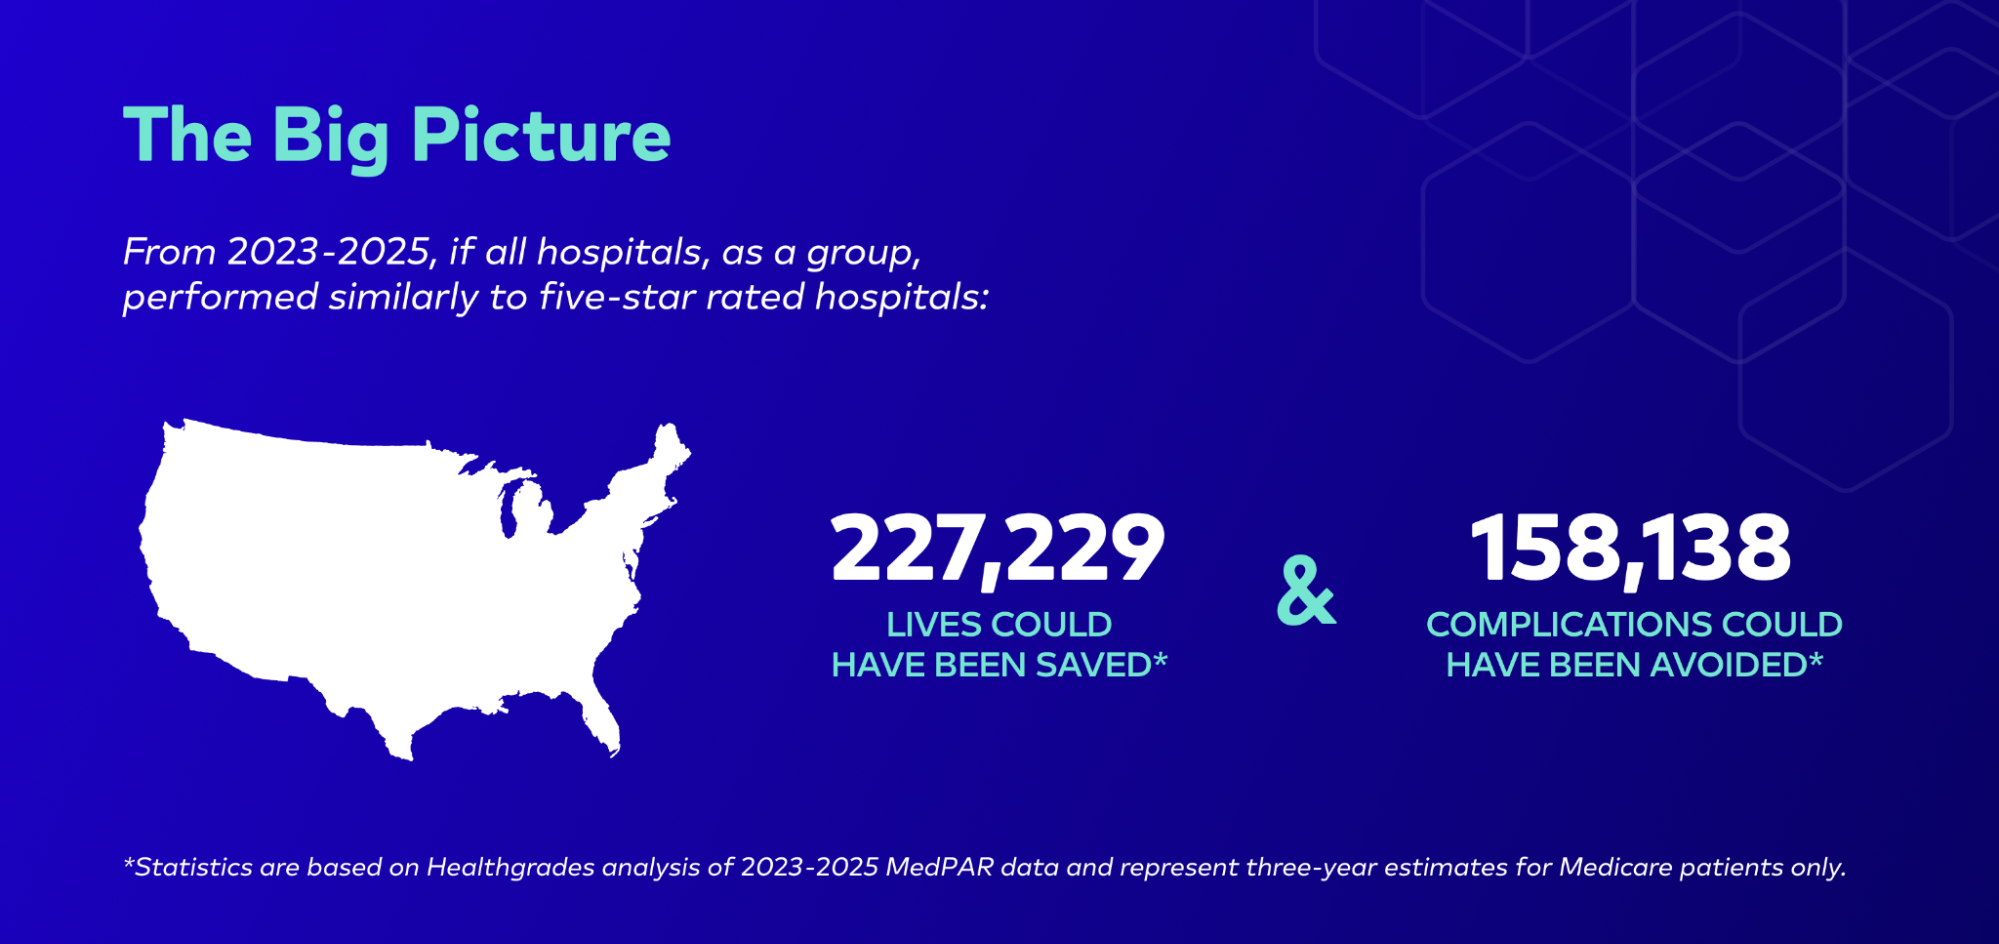
This year’s findings also identified similar disparities in clinical quality at the local level, including significant performance gaps among hospitals within the same city.
The Financial Outlook
Despite the cautious optimism signaled by year-end financial reports, the first six months of 2026 marked an end to the relative stability and improvements realized in the latter half of 2025. At the national level, hospital expenses continue to grow exponentially, with Kaufman Hall noting a 21% YTD increase in total spending since 2023. Revenue growth has followed a similar trajectory, with the nation’s hospitals reporting a 24% YTD increase in net operating revenue over the same three-year period.
Although revenue growth continues to outpace spending, these national aggregates often obscure the vulnerability of individual hospital balance sheets. In fact, nearly half of all U.S. hospitals are currently in the red as they strive to meet rising demand for care from a patient population that is sicker, more complex, and less likely to be insured.
Key operational pressures include:
- Non-Labor Inflation: While clinical labor costs have largely stabilized, input expenses have surged. The American Hospital Association estimates that higher input costs–including labor, supplies, and drugs–accounted for 45% of all recent expenditure increases. In 2025 alone, expenses for hospital supplies grew by 9.9% and drugs by 13.6%–both outpacing standard price indexes.
- Rising Uncompensated Care: Coverage losses are worsening. According to Commonwealth Fund tracking, the uninsured rate among working-age adults (ages 19-64) hit 11.2% in July 2026 amid ongoing insurance exchange disenrollments. With the Congressional Budget Office projecting the number of uninsured Americans to reach 37 million over the next decade, charity care and bad debt burdens will remain a persistent headwind.
To remain viable, healthcare leaders must pivot from blunt cost-cutting toward dynamic cost-containment strategies aimed at capturing high-margin elective specialty volumes, operationalizing non-acute sites of care, and deploying administrative AI.
Shifting Care Preferences
Coverage declines and rising premiums are hurting hospitals in more ways than one. Major for-profit health systems reported lower surgical volumes in the first half of 2026, especially for elective procedures. While organizations have seen demand dip both within and beyond hospital walls, ongoing shifts toward non-acute care settings could undercut earnings for those that fail to make their presence known in the outpatient market.
Demand for outpatient care predates the pandemic and continues to grow as the cost of care rises, with recent Sg2 projections indicating a 20% increase in overall outpatient volumes over the next 10 years. Significant shifts are already underway in specific service areas, including orthopedics. Healthgrades’ 2027 analysis revealed that outpatient volume growth currently outpaces inpatient volumes for two critical procedures:
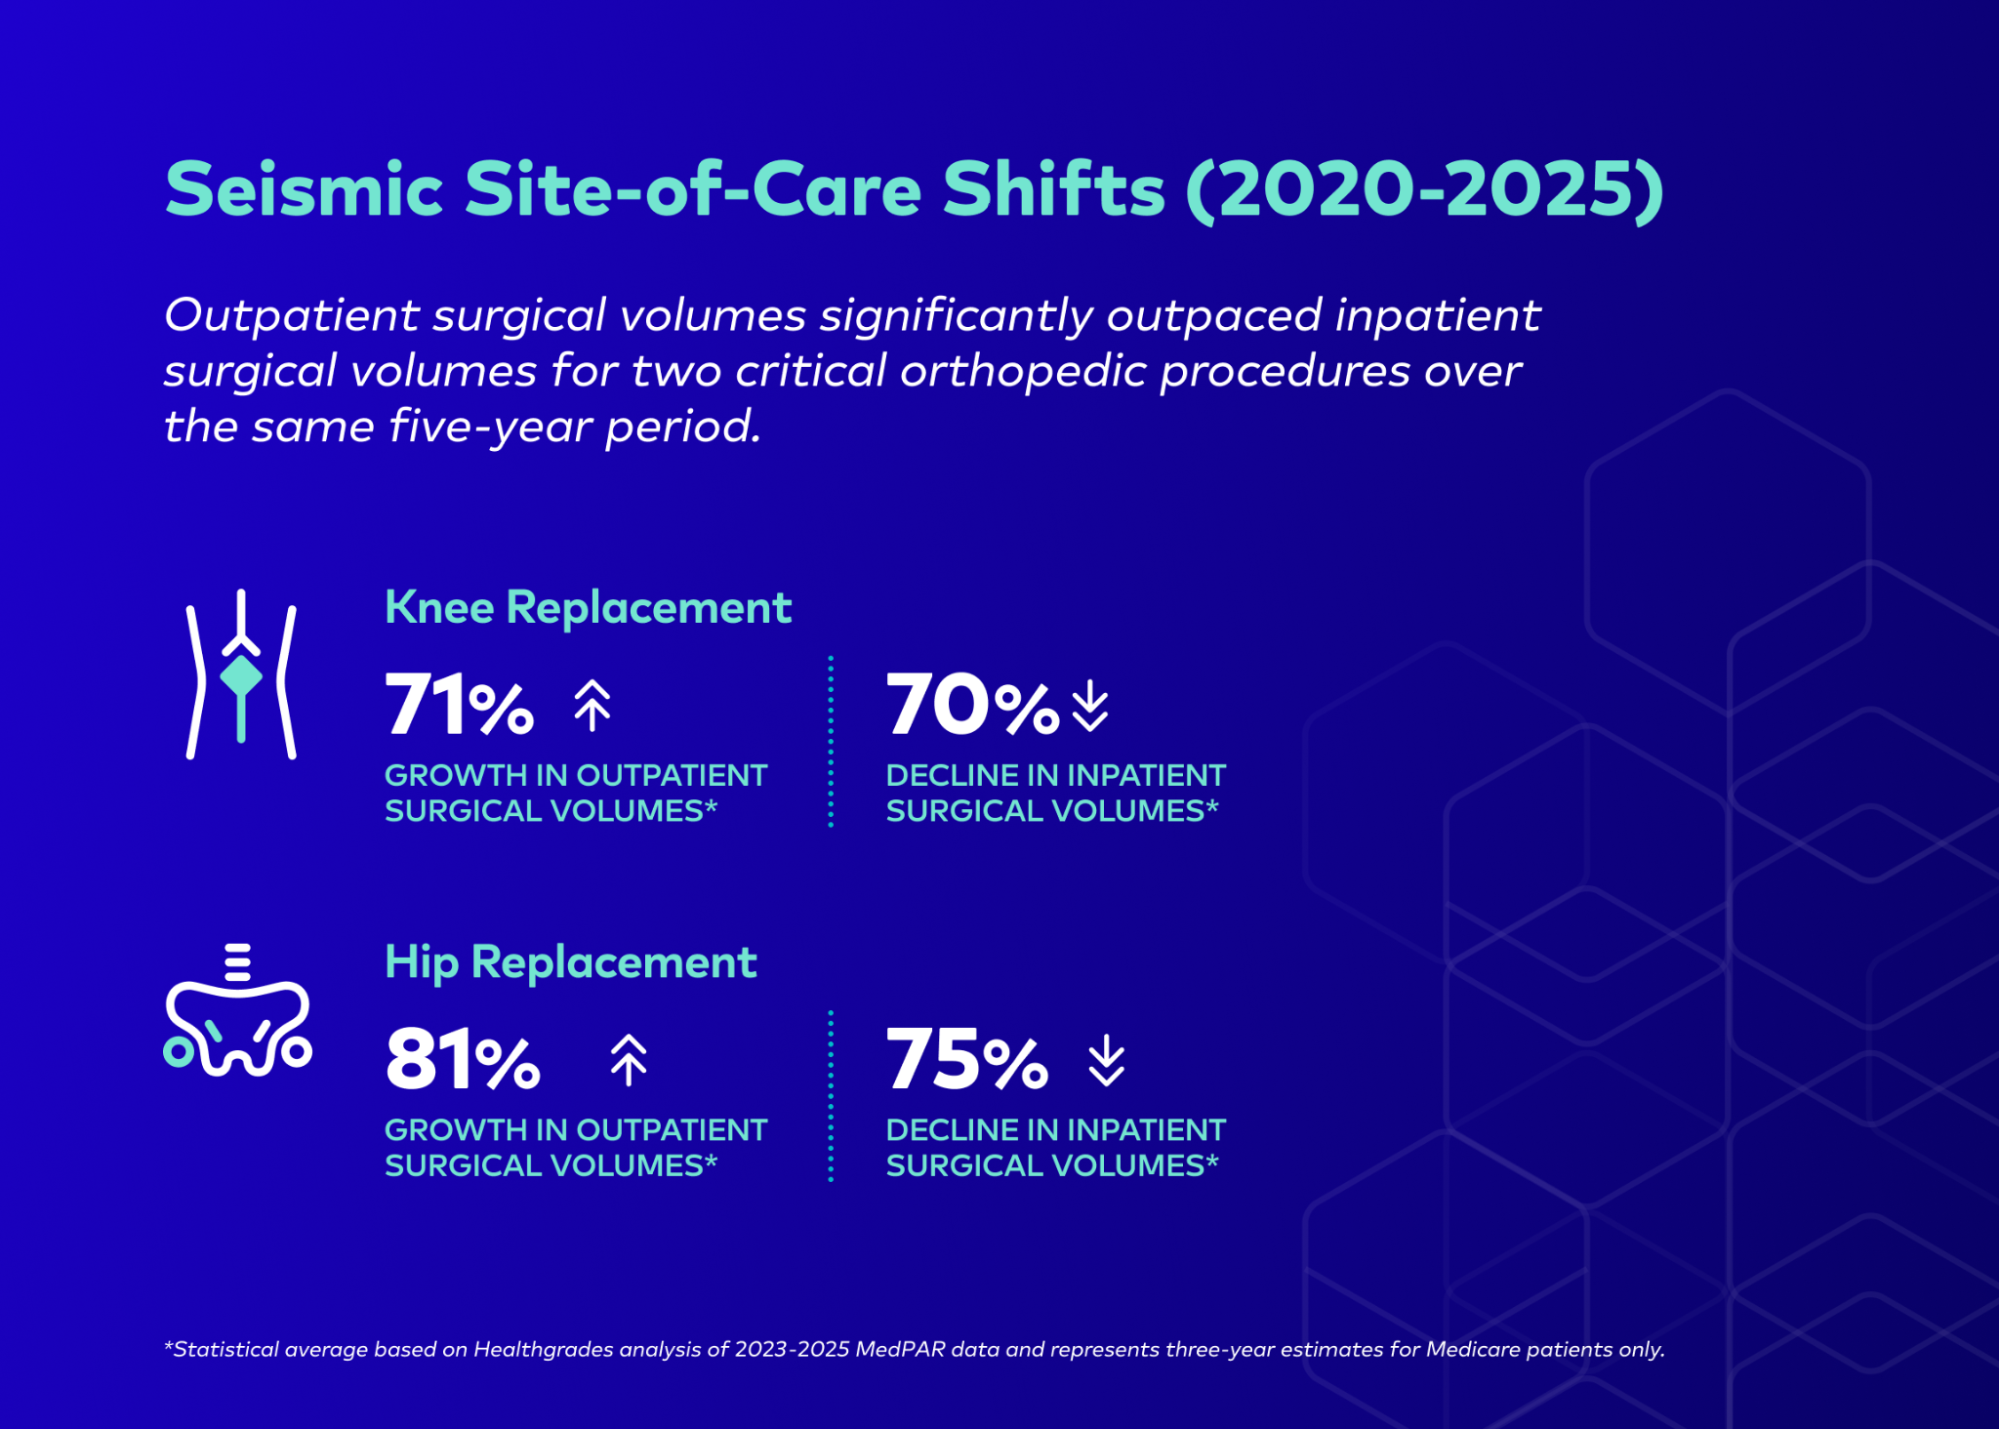
For industry stakeholders, these site-of-care shifts represent a $50 billion opportunity to recoup losses from declines in inpatient volume and to engage cost-conscious consumers who deferred care in H1. Larger health systems have a considerable advantage in mitigating the financial impact of outpatient migration. However, there is still an opportunity for those unable to shoulder the burden of facility expansion alone. Shared referrals and volume trading through partnerships and affiliations are just two ways smaller healthcare providers can recapture inpatient revenue losses without compromising existing services.
AI-Powered Operational Efficiency
AI utilization represents another revenue opportunity for hospitals, and a growing number of organizations are integrating advanced technology into their day-to-day operations. Research published by Menlo Ventures found that AI healthcare investment tripled between 2024 and 2025, with providers accounting for roughly 75% of that capital deployment.
Administrative overhead remains a critical factor in workforce attrition, costing the industry an estimated $4.6 billion annually. Large language models (LLMs) deployed within EHRs and patient portals automate clinical documentation, pre-authorization filings, and routine inbox triage—returning meaningful hours to direct patient care.
As systems mature beyond stand-alone chatbots and reactive generative AI models, 2027 will see the adoption of agentic AI workflows capable of cross-referencing payer rules, scheduling complex specialty care, and flagging for clinical follow-up without manual intervention.
A Note on Healthgrades Methodologies
Healthgrades awards and ratings are not a popularity contest: Healthgrades does not consider a hospital’s reputation or financial standing when evaluating performance, and hospitals cannot opt in or opt out of the assessment process. This approach allows hospitals and consumers to stay focused on what matters most: patient outcomes.
To learn more about how Healthgrades rates hospitals, view the complete methodologies:
- 2027 Specialty State Rankings Methodology
- 2027 Specialty Excellence Awards Methodology
- 2027 Outpatient Awards Methodology
Footnotes
1In order to qualify for state rankings, a state must have at least 7 hospitals that meet the eligibility requirements. A Top 3 is identified when there are more than 7 but fewer than 11 eligible hospitals; a Top 5 is identified when there are 11 or more eligible hospitals. To learn more about how Healthgrades determines the state leaders in specialty, see Healthgrades’ 2027 Specialty State Ranking Methodology.
2Healthgrades Research, n=1000, April 2026.